How to Qualify for a Mortgage After Bankruptcy in Canada

Tanya Toye • July 29, 2026

Financial setbacks happen.


Bankruptcies and consumer proposals are more common than most people realize—and they don’t define your future.


Going through one doesn’t mean homeownership is off the table forever. It simply means lenders want to see that you’ve taken control, learned from the past, and built a stronger financial foundation moving forward.

What lenders look at after a bankruptcy or consumer proposal


How long it’s been since your discharge
Your discharge date matters. For lenders, this is your reset point. There’s no law that says you must wait a specific amount of time before applying for a mortgage, but the longer your track record after discharge, the stronger your application becomes. What matters most is how responsibly you’ve managed your finances since then.


Your credit rebuild
Re-establishing credit is critical. After discharge, most people start with a secured credit card and use it consistently and responsibly.


To be considered fully re-established, lenders typically want to see:

  • Two active trade lines
  • At least two years of clean payment history
  • Credit limits of around $2,500 on each
  • No late or missed payments


Your down payment or equity
The more money you can put down—or the more equity you have when refinancing—the lower the risk for the lender. A stronger down payment often opens the door to better terms and more lender options.


Your debt service ratios
Lenders will also look closely at how much of your income goes toward housing and other debts. The stronger your income relative to your monthly obligations, the easier it is to qualify.


Conventional vs. insured mortgage options


To access the most competitive mortgage products, lenders typically want to see:

  • At least two years plus one day since discharge
  • Fully re-established credit
  • Minimum down payment requirements met
  • Mortgage insurance in place if your down payment is under 20% (through CMHC, Sagen, or Canada Guaranty)
  • Total debt obligations generally not exceeding 44% of your gross income


Alternative lending options


Not every situation fits neatly into a bank’s box—and that’s where alternative lending can help.

Independent mortgage professionals work with both traditional and alternative lenders, including those who specialize in complex financial situations. These lenders look at the full picture: equity, income stability, and your plan moving forward.


While rates and terms may not be as competitive as prime lending, alternative financing can be an effective short-term solution—especially if you need a mortgage before your credit is fully rebuilt.


Let’s talk about your next step


Whether you’re planning ahead for the best possible mortgage—or need a solution sooner rather than later—there are options available.


If you’d like help mapping out a clear path forward, reach out anytime. I’d be happy to review your situation and help you build a plan that gets you back into homeownership with confidence.
Tanya Toye

Mortgage Broker

GET STARTED
By Tanya Toye • October 21, 2026
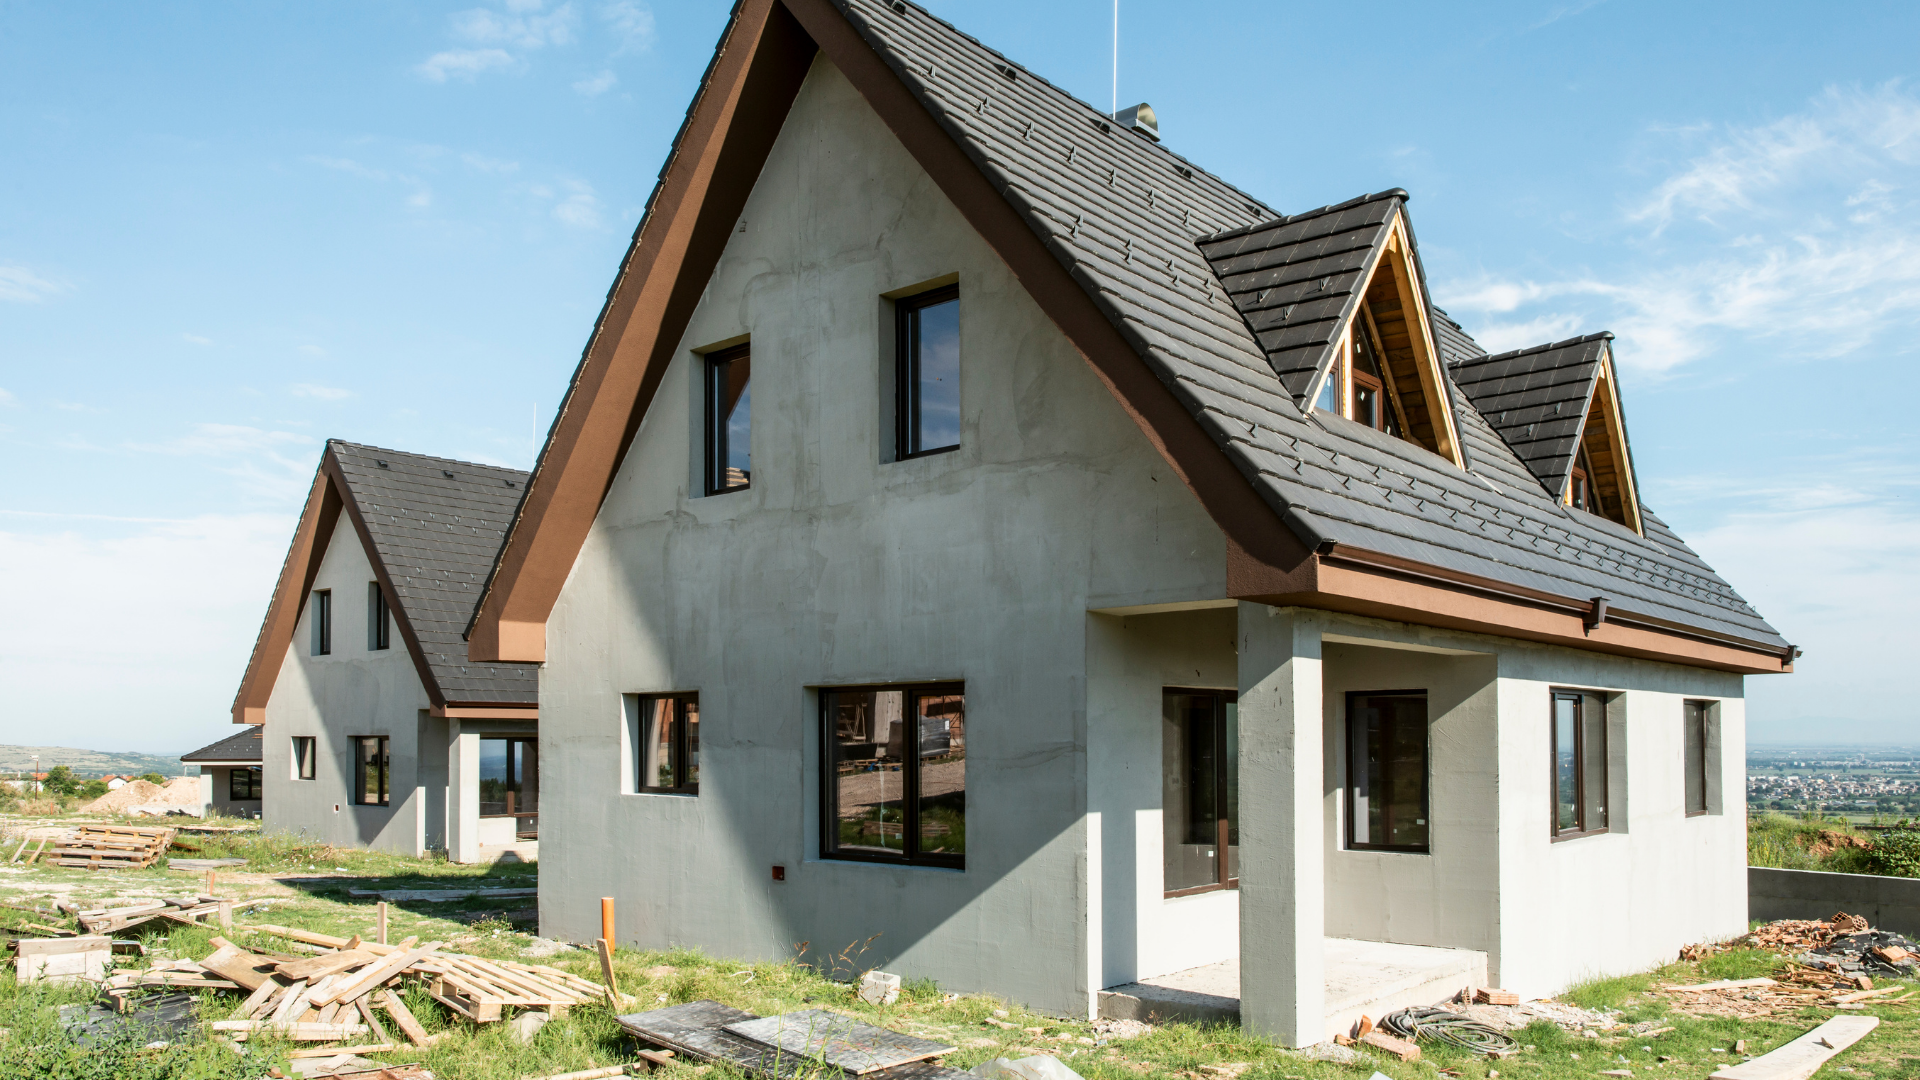
Why More Mortgage Options Matter—Especially for Assignment Purchases One of the biggest advantages of working with an independent mortgage professional is access to choice. Instead of being limited to one lender and one set of products, mortgage brokers work with multiple lenders—each with different guidelines, risk tolerances, and mortgage solutions. That flexibility becomes especially valuable when your situation doesn’t fit neatly into a “standard” box. A great example of this is purchasing new construction through an assignment contract . Why Assignment Purchases Can Be Challenging Assignment purchases are often viewed as higher risk by traditional lenders. Rather than declining these deals outright, many lenders quietly make them difficult by adding layers of conditions, restrictions, or uncertainty. This can lead to delays, frustration, or financing falling apart late in the process. The Good News There are lenders—available exclusively through the broker channel —that have clear, favourable policies for assignment purchases. With the right lender and proper planning, these transactions are absolutely doable. Typical Financing Requirements for Assignment Purchases While every situation is unique, many lenders that allow assignment financing look for the following: Standard purchase qualification, including income verification, credit, and down payment Assignments accepted at either the original purchase price or current market value Minimum 620 credit score , with no prior bankruptcies or consumer proposals The full down payment must come from the purchaser —seller incentives cannot be used Required Documentation To secure financing, lenders typically require: The original purchase agreement signed by all parties The MLS listing (if applicable) The assignment agreement signed by the builder, original purchaser, and new buyer Any side agreements outlining changes to the purchase price A full appraisal to confirm value This list isn’t exhaustive, but it highlights that while assignment purchases require more coordination, they are very achievable with the right lender and guidance. Final Thoughts Assignment contracts can open doors to great opportunities—but only if your financing supports the transaction. This is where access to multiple lenders and specialized policies makes a real difference. If you’re considering purchasing new construction through an assignment, or if you’d like to explore more traditional purchase options, feel free to connect anytime. I’d be happy to walk you through the mortgage products available and help you choose an option that doesn’t limit your financing possibilities.
By Tanya Toye • October 14, 2026
What Online Mortgage Calculators Can—and Can’t—Tell You Online mortgage calculators are everywhere—and on the surface, they seem like a no-brainer. You plug in some numbers, and out pops what you can “afford.” Simple, right? Not quite. While the math itself is correct, the story behind those numbers is often misleading. Mortgage qualification isn’t just about numbers—it’s about context, risk, and lender policy. And that’s where calculators fall short. The Numbers Are Accurate—but the Picture Isn’t An online calculator can show you what a payment might look like at a given interest rate, or how making extra payments could reduce your amortization. That’s useful information! But when it comes to mortgage qualification , calculators don’t account for the many variables that lenders consider, such as: Your credit history and score Employment type (salary, self-employed, contract) Outstanding debts and monthly obligations Assets, savings, and down payment source The property type and location you’re buying Lenders evaluate all these factors through their internal risk models. That means two people entering the exact same numbers into a calculator could receive very different results when they actually apply for a mortgage. Why Online Calculators Can Mislead You When you see a “How much can I afford?” or “Mortgage Qualification” calculator online, it’s easy to treat the result as fact. But these tools don’t know your financial story—they only crunch the data you enter. A calculator can’t predict how a lender views your risk, how new mortgage rules apply to your file, or how things like spousal support, car loans, or variable income will impact approval. In short: calculators estimate payments, not qualification . Use Calculators the Right Way Don’t get us wrong—online calculators still have value. Use them to explore different “what-if” scenarios: How do payments change with different down payment amounts? How would a rate increase affect affordability? What if you added $100 a month to your payments? These tools are great for helping you understand your comfort zone. Just remember: they’re a starting point, not a green light. The Real First Step: Get a Pre-Approval If you’re serious about buying a home, skip the guesswork and get a mortgage pre-approval . It’s quick, free, and gives you real-world clarity on what you can afford. A pre-approval looks at your full financial picture—income, credit, debts, assets—and provides a framework for your purchase price, payment range, and rate options. It’s the only way to get a reliable answer to the question, “What can I really afford?” Final Thoughts Online calculators are convenient, but they can’t replace expert advice. Think of them as a starting point, not a solution. A professional mortgage broker can interpret the numbers, navigate lender policies, and tailor your financing strategy to your actual situation. If you’d like help understanding your true buying power—or want to get pre-approved with confidence— reach out anytime . I’d be happy to walk you through your options and help you make sense of the numbers.